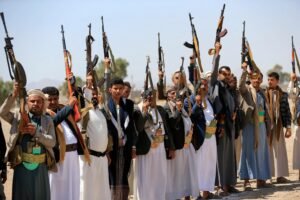

Global energy markets continued monitoring escalating Houthi attacks against Saudi Arabian targets this week, with traders closely watching how this persistent regional instability might affect broader oil supply dynamics even as the immediate attacks have primarily targeted power infrastructure and military positions rather than directly disrupting major oil production or export facilities. The sustained pattern of ballistic missile launches, several of which Saudi-led coalition forces have successfully intercepted, continues adding a persistent risk premium to energy market pricing throughout this period of heightened regional tension.
Saudi Arabia has responded to this continued Houthi threat with substantial financial commitment to Yemen’s government forces, providing approximately sixty million dollars specifically earmarked to support the fight against Houthi militants. This financial support illustrates Saudi Arabia’s continued significant investment in countering the Houthi threat through supporting allied Yemeni government forces, representing an approach that extends beyond purely defensive military measures to actively funding the broader counter-Houthi military effort within Yemen itself.
Energy analysts note that while these specific Houthi attacks have not directly targeted major oil production or export infrastructure, the broader pattern of regional instability continues contributing to the elevated risk premium built into current oil pricing. Markets remain acutely sensitive to any signs that this conflict could potentially expand to more directly threaten critical energy infrastructure, given Saudi Arabia’s position as one of the world’s most significant oil producers and exporters.
The continued Houthi military activity occurs within the broader context of the extended Iran-related regional conflict, with Houthi forces representing one of several Iran-aligned groups operating across different fronts throughout the Middle East. This interconnected web of regional conflicts, all tracing back to varying degrees to the broader Iran-related tensions, creates a complex web of potential escalation pathways that energy traders must continuously monitor when assessing overall regional stability and its implications for global oil supply security.
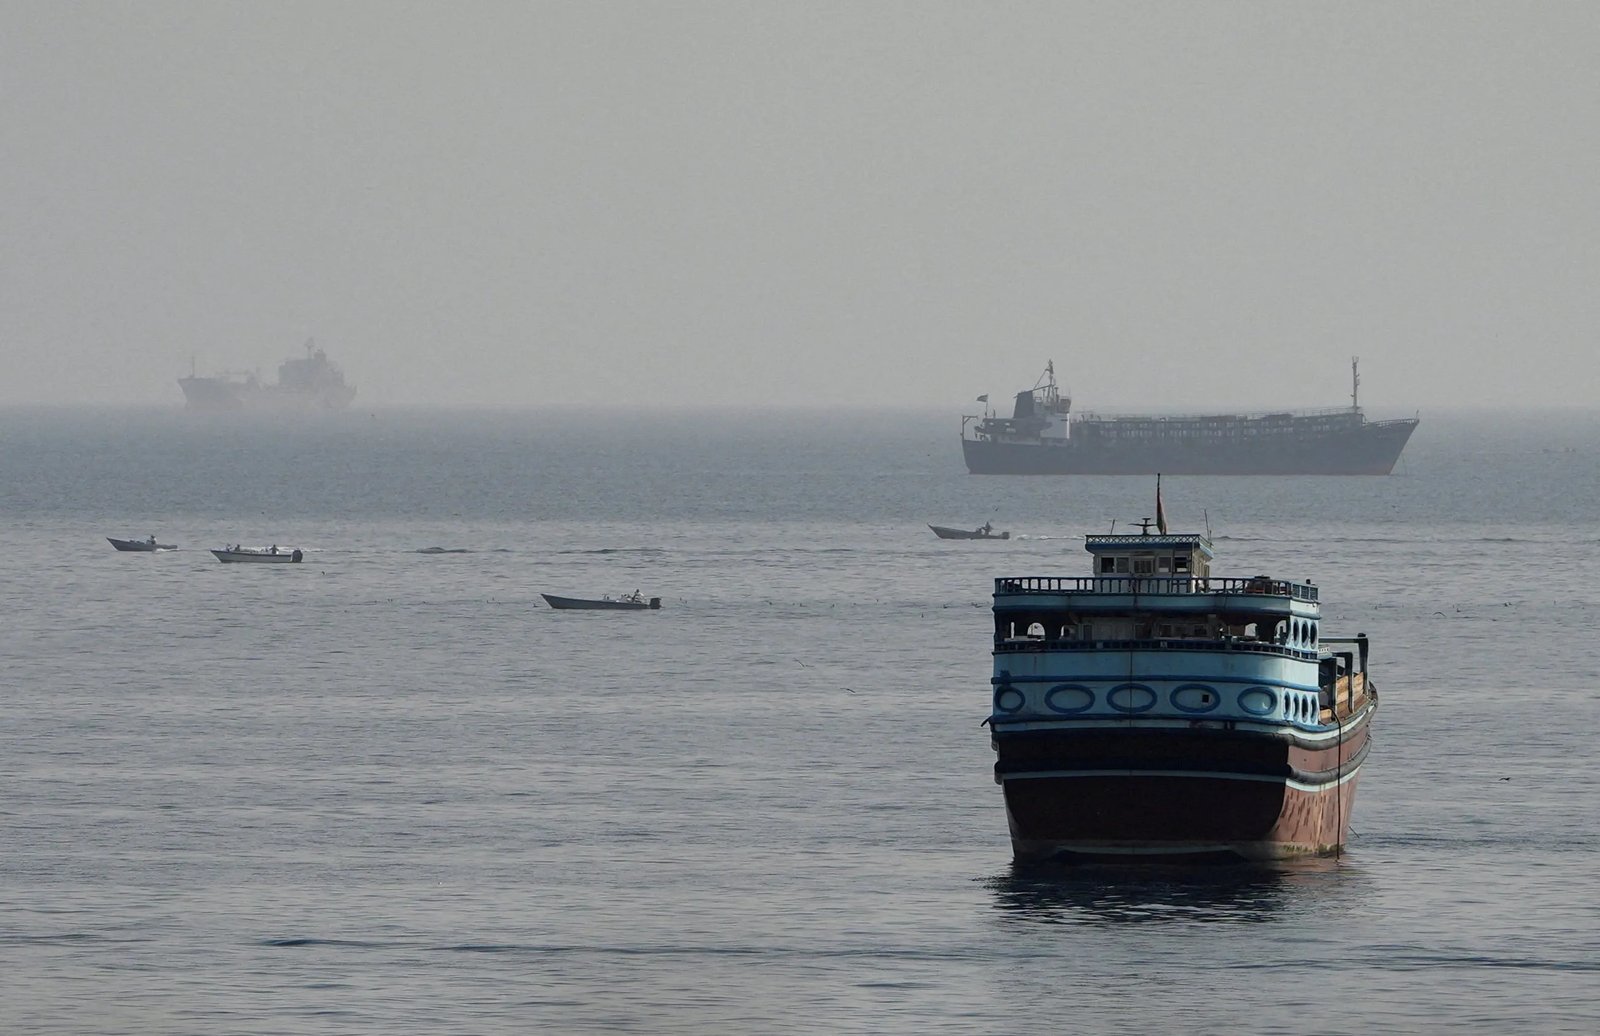
Saudi Arabia’s continued ability to maintain strong oil export volumes despite these ongoing security challenges, a pattern that has persisted throughout much of this extended regional conflict, has provided some reassurance to energy markets even amid the continued attacks. This demonstrated resilience in maintaining export capacity, even while simultaneously managing active security threats, illustrates the substantial redundancy and operational flexibility built into Saudi Arabia’s energy infrastructure and export logistics systems.
Market strategists continue emphasizing that the relationship between regional security incidents and actual oil price movements has become considerably more nuanced throughout this extended conflict period, with markets increasingly distinguishing between incidents that pose genuine threats to actual oil supply versus those representing primarily political or military developments without direct energy infrastructure implications. This more sophisticated market response reflects traders’ accumulated experience navigating numerous similar incidents throughout the conflict’s extended duration.
As this pattern of continued Houthi attacks and Saudi counter-measures persists without clear resolution, energy markets are likely to remain in a state of heightened but manageable vigilance, pricing in continued risk without necessarily triggering the kind of dramatic price spikes that might accompany a more direct threat to actual oil production or export infrastructure. Whether this pattern eventually escalates to more directly threaten energy supply, or continues as a persistent but contained regional security challenge, will likely become clearer as this extended conflict continues developing in the coming weeks and months.